Extreme weather is creating financial risks for companies, infrastructure, and portfolios, while asset owners are increasingly forcing investment managers to explain how they account for those risks.
For years, the debate over climate investing was largely framed as a political argument. Should investors use their money to fight climate change? Should pension funds prioritize environmental goals? Should asset managers join campaigns pushing companies toward lower emissions?
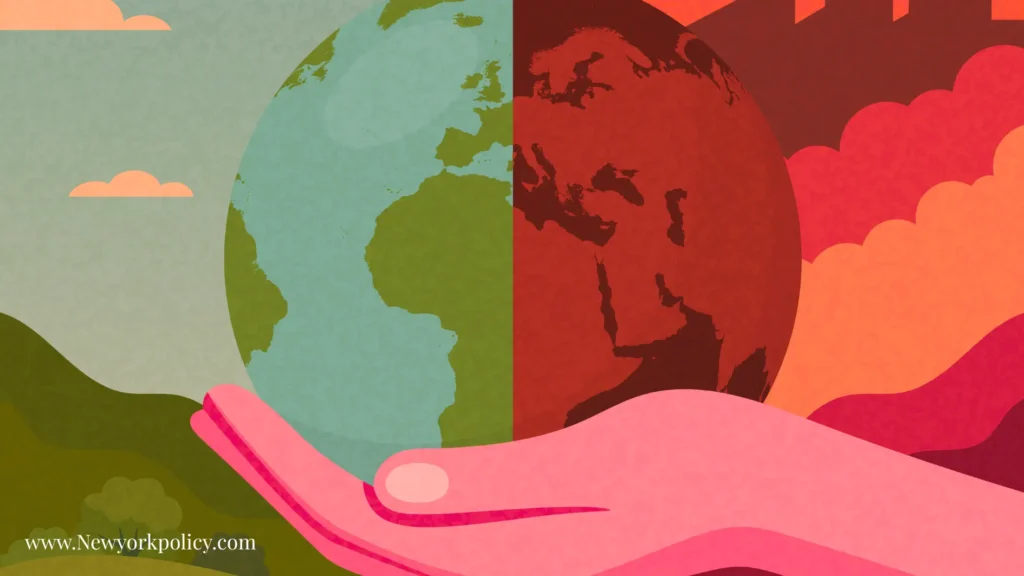
But the financial question underneath all of that is getting harder to avoid. Wildfires, extreme heat, drought, and other climate-related events can damage physical assets, interrupt supply chains, drive up insurance costs, and eat into corporate profitability. Climate change isn’t only an environmental issue anymore — it’s also a question of portfolio risk.
A recent decision by the UK’s Nesta Trust illustrates how that debate is evolving. The trust moved £120 million in passive global equity assets from Northern Trust Asset Management to the European investment manager Amundi, saying it wanted its investments to better support climate action. That amount represented more than a quarter of Nesta Trust’s entire portfolio.
The move itself is small in global financial terms, but the signal is bigger than the number suggests: some asset owners are now willing to switch managers outright when they decide a manager’s approach to climate stewardship no longer matches their own long-term goals.
Climate Risk Is Moving From Theory to Portfolio Reality
The traditional case for factoring climate risk into investment decisions was fairly simple. If governments tighten emissions rules, carbon-intensive companies could face higher costs. If consumers shift toward cleaner technologies, some business models could lose market share. If investors see those changes coming, asset prices might adjust before the physical effects even show up.
Now a different category of risk is getting more attention: physical climate risk. Floods, wildfires, droughts, storms, and extreme heat can directly damage factories, buildings, infrastructure, and agricultural production, and they can disrupt transportation networks and supply chains along the way. Amundi’s own research has warned that physical climate risk is still less developed in investment analysis than transition risk, even though extreme weather and ecosystem disruption are already affecting asset values and supply chains today.
That distinction matters. An investor doesn’t need to believe every climate policy will succeed to conclude that physical climate damage belongs in a risk assessment.
The Nesta Decision Shows Where Asset Owners Have Leverage
Nesta Trust’s decision is a clear example of how large asset owners can push back on the industry. The trust said Northern Trust’s withdrawal from the Net Zero Asset Managers Initiative and Climate Action 100+ was incompatible with its own sustainability objectives, and moved its global equity portfolio to Amundi as a result.
Amundi, for its part, has continued to position itself around climate transition and shareholder engagement — its 2025–2028 climate strategy includes product development, company engagement, and other measures meant to work climate considerations into investment decisions. The point here isn’t that Amundi has somehow solved climate investing. It’s that asset owners have another lever available when they disagree with how a manager approaches stewardship: they can simply move the money. For pension funds, foundations, and endowments with long investment horizons, that threat carries real weight.
The U.S. and Europe Are Moving in Different Directions
The investment industry is increasingly having to operate across very different political environments. In parts of Europe, climate considerations remain closely woven into financial regulation, institutional investing, and corporate governance. In the United States, the political environment has grown considerably more polarized, and some asset managers have pulled back from industry climate alliances amid political and legal pressure.
That doesn’t necessarily mean American investors have stopped analyzing climate risk. Northern Trust’s own 2026 sustainable-investing research says investors are weighing climate resilience, resource constraints, and other sustainability-related factors as influences on markets, treating climate risk as part of a broader risk-management framework rather than a standalone cause.
That creates an important distinction: leaving a climate coalition is not the same thing as eliminating climate risk from a portfolio. A manager can scale back its public involvement in ESG initiatives while still weighing extreme weather, the energy transition, regulation, resource scarcity, and other factors that could affect returns. That distinction is only likely to matter more going forward.
The Real Issue Is Not ESG. It Is Risk Management.
The term ESG has become politically loaded. For some investors, it represents an important framework for understanding long-term risk. For others, it’s become tangled up with political preferences that, in their view, shouldn’t be driving investment decisions.
But strip the label away and the underlying problem doesn’t change. A company whose factory keeps flooding has a financial problem regardless of what its investors call it. An insurer facing rising wildfire claims has a financial problem. A manufacturer dependent on a water-stressed region has a financial problem. A utility running infrastructure exposed to extreme heat has a financial problem. The investment question becomes more basic than ESG politics: are these risks being priced correctly? That’s a much harder question to wave away as ideology.
The Data Problem Is Still Significant
There’s also a reason investors can’t simply treat climate risk as a clean calculation. Climate models carry real uncertainty. Companies operate across different regions and supply chains. The timing of physical damage is hard to predict. And financial impacts can show up indirectly — through insurance prices, commodity markets, migration, infrastructure spending, or government policy — rather than showing up on a balance sheet directly.
Amundi’s research acknowledges that measuring physical climate risk is considerably more complicated than measuring traditional transition indicators; there’s still no universally accepted equivalent of a simple carbon-intensity metric for physical risk.
That means sophisticated investors increasingly need forward-looking analysis rather than leaning on historical data alone. Northern Trust’s 2026 research makes a similar point, arguing that investors are increasingly turning to forward-looking climate scenarios and newer measures of physical and transition risk. The challenge is making those models genuinely useful without pretending they’re more certain than they are.
Pension Funds Have a Different Clock
The issue matters especially for pension funds and endowments. A short-term investor might be focused mainly on the next quarter or the next few years. A pension fund, by contrast, may be responsible for assets and liabilities stretching decades into the future — which gives it a fundamental reason to care about risks that develop slowly rather than all at once.
A company can look financially attractive today while growing steadily more exposed to physical or regulatory change over a much longer horizon. For long-term asset owners, ignoring that possibility can itself become a form of risk-taking. That doesn’t mean pension funds should sacrifice returns in the name of environmental goals — it means they may increasingly need to ask whether environmental risks are actually being priced into the return calculation in the first place.
The Next Battle May Be Over Stewardship
The biggest shift underway may not be money moving between individual asset managers. It may be the growing pressure on managers to explain how they vote, how they engage with companies, and how they manage long-term risk on behalf of their clients. Amundi reported engaging nearly 3,000 companies through direct dialogue in 2025, reflecting the growing role stewardship now plays in its responsible-investment strategy.
That raises another question for asset owners: if they hold shares through a large passive fund, they can’t easily sell off every company they consider problematic — their influence instead runs through the manager’s voting and engagement choices. That makes stewardship unusually important. The question isn’t just what companies an investor owns. It’s what the investor actually does with the ownership rights attached to those shares.
Climate Politics May Change. Physical Risk Will Not Follow the Election Cycle.
This may be the uncomfortable reality underneath all of it: political attitudes toward climate policy can shift quickly, but investment portfolios can’t shift nearly as fast. A new administration can rewrite regulations. A political campaign can change the language around ESG.
Asset managers can quit industry alliances. But a wildfire can still destroy physical assets. A drought can still disrupt agricultural production. Extreme heat can still degrade infrastructure. None of those risks disappear just because the political conversation moves on.
That’s why the distinction between climate policy and climate risk is becoming more important for investors, not less. An institution can oppose a specific climate regulation and still believe that physical climate damage represents a material financial risk — the two positions aren’t in tension.
The Money May Eventually Decide the Debate
Nesta Trust’s £120 million transfer isn’t large enough on its own to reshape global markets. But institutional investment decisions rarely need to be enormous individually to matter collectively. If more pension funds, foundations, and endowments start shifting capital toward managers whose climate-risk policies they see as stronger, asset managers will have a straightforward economic incentive to respond. And if other institutions conclude that climate initiatives conflict with their fiduciary duties or investment goals, capital could just as easily move the other way.
The likely result isn’t a universal shift toward one version of ESG investing — it’s more of a competition between investment philosophies. Whichever approach wins out will still have to answer the same underlying question: how do you protect and grow long-term capital in a world where climate-related risks are becoming harder and harder to ignore? That question is bigger than ESG, and for investors thinking in decades rather than quarters, it may simply be unavoidable.
Author